The Idiot Index: Where Price Drifts Furthest From Substance
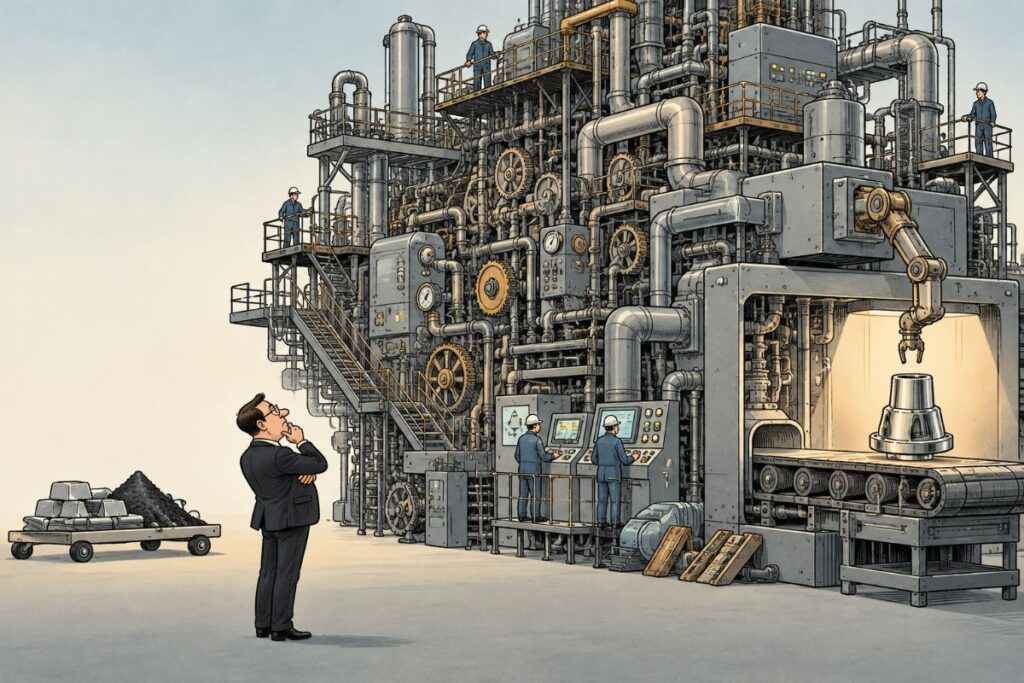
Elon Musk, founder and chief executive of SpaceX, uses a test he calls the idiot index: the total cost of a component divided by the cost of its raw materials. If the materials cost $100 and the finished part $1,000, the design is probably too complex or the manufacturing too inefficient. Walter Isaacson’s biography of Musk, as recounted in a review by The Globe and Mail, describes a meeting on SpaceX’s Raptor engine where Musk asked a financial analyst which parts scored worst. The analyst knew the cost of every part but not the cost of the materials inside them. When he estimated a nozzle component at a few thousand dollars, Musk replied that it was just steel, worth about two hundred (The Globe and Mail, 2023).
The name is provocative, but a wide gap between price and substance is rarely proof that anyone is stupid. More often it marks a closed market, one where few buyers, few sellers, low volumes and high stakes let price drift away from the cost of production and stay there. These gaps are not a curiosity. They help set what governments pay for defence, what health systems pay for medicines and what utilities pay to connect new data centres. Where a gap is wide and stable, it decides who earns the returns. Where it starts to move, it shows where an entrant may have room. Several such markets are moving now, some narrowing and some widening. This piece does not rank them. It describes what they have in common.
Musk’s index is an engineering tool: it compares one component with its materials, and a high reading points at the design or the factory. This article borrows it more loosely, to compare what buyers pay with what a product plausibly costs to make. That wider gap has different sources. One is manufacturing inefficiency, which is what Musk was hunting. Another is patents, which deliberately allow pricing above cost for a fixed term. A third is scarcity premiums, which last until capacity catches up. The last is real costs that a materials list leaves out, such as testing, certification and failed research. The cases below are not calculations of one ratio. They show when price and production cost drift apart, and what brings them back together.
Space launch shows how long such a gap can last. Harry W. Jones, a systems engineer at NASA’s Ames Research Center, compared launch costs across the history of spaceflight. After a steep fall in the first decade of the space age, the average cost of putting a kilogram into low Earth orbit stayed roughly flat between 1970 and 2000, at about $18,500 in 2018 dollars. On the same basis, the Space Shuttle cost around $61,700 per kilogram and SpaceX’s Falcon 9, using its advertised price, about $2,700, roughly a twentieth of the Shuttle (Jones, 2018). Jones’s explanation is the instructive part. The technical causes of high launch costs had long been understood: performance prioritised over cost, very low tolerance for failure and the heavy oversight that follows, and high complexity and parts counts. Remedies had been proposed for decades. What delayed them, he argues, were cultural and institutional barriers, until commercially motivated suppliers bypassed the problems that had held back government-sponsored rocket builders.
The same conditions recur wherever price stays far above production cost. There are few buyers, often a government, or few sellers, sometimes a single one protected by a patent. Volumes are low enough that every unit is close to handmade. The stakes are high enough that requirements accumulate and are rarely removed. And often nobody has done the arithmetic. If the gap can go unmeasured inside the company that popularised the index, it can easily go unmeasured in an industry that has never asked.
What narrows the gap varies with what caused it. In launch, according to Jones, costs did not fall because established builders finally adopted known remedies. They fell because commercial entrants, answerable to paying customers rather than to government programmes, built rockets differently.
In medicines, the gap is partly by design, and the opening arrives on a known date. In 2024, researchers led by Melissa Barber used trade data on active ingredients to estimate sustainable cost-based prices for diabetes medicines, including a margin for the manufacturer. For injectable semaglutide, the active ingredient in Novo Nordisk’s Ozempic and Wegovy, they estimated roughly $0.89 to $4.73 a month at the standard diabetes dose, against lowest market prices of $38 to $354 a month across the twelve countries they surveyed in early 2023 (Barber et al., 2024). Those estimates leave out the research costs that patents are meant to repay, which is precisely the bargain a patent embodies. When the semaglutide patent expired in India in March 2026, at least half a dozen Indian drugmakers launched versions within days, cutting treatment costs by about 70 percent according to Reuters (Reuters, 2026). The Hindu BusinessLine reported that some of the first versions were priced more than 80 percent below Ozempic (The Hindu BusinessLine, 2026). In May, Canada became the first G7 country to approve a generic semaglutide injection, which was expected in pharmacies from June at less than a third of the cost. The BBC also reports that the Indian launches prompted Novo Nordisk to cut its own prices there by nearly half (BBC, 2026).
In batteries, volume and competition did the work. BloombergNEF, the energy research provider, put the average lithium-ion pack price at $108 per kilowatt-hour in 2025, 93 percent below 2010. The more revealing detail is that pack prices fell in 2025 even though battery metal prices rose. BloombergNEF attributes the decline to cell overcapacity, intense competition and a shift to cheaper lithium iron phosphate chemistry (BloombergNEF, 2025). The price fell while the materials became more expensive, which is what an opened market looks like.
The gap can also widen. When demand jumps faster than supply can follow, buyers pay a scarcity premium. In October 2023 Admiral Rob Bauer, NATO’s senior military officer, said a 155-millimetre artillery shell had risen from €2,000 before Russia’s attack on Ukraine to €8,000 (Reuters, 2023; Defense One, 2023). The figure is disputed: a year later a senior industry executive told Defense News that Western European shells cost between $5,000 and more than $10,000 depending on type (Defense News, 2024). Grid equipment shows a similar pattern with better data. Wood Mackenzie, an energy research consultancy, estimates that US power transformer prices have risen 77 percent since 2019 as data centres, electrification and an ageing grid compete for limited factory capacity (Wood Mackenzie, 2025). In its assessment, prices kept rising after raw material costs eased, because suppliers raised their margins (Wood Mackenzie, 2024). A premium of this kind can be a passing windfall for incumbents. It is also a public signal of where new capacity would be paid for.
Defence shows both directions at once, and Finland, which joined NATO in April 2023, sits close to the change (NATO, 2023). The Center for Strategic and International Studies (CSIS), a Washington think tank, cites estimates that a Shahed attack drone costs $20,000 to $50,000, while a Patriot PAC-3 interceptor costs more than $3 million (Jensen and Atalan, 2025; Hollenbeck et al., 2025). CSIS has also warned that such comparisons mislead, because interceptors are expensive mainly due to the technical demands of hitting a target in flight (Rumbaugh, 2024). The response in Ukraine has not mainly been a cheaper interceptor. According to CSIS, Ukraine has increasingly relied on electronic warfare to degrade drone accuracy rather than shooting every drone down (Jensen and Atalan, 2025). The gap narrowed through a different way of doing the job, not a cheaper copy of the old product.
ICEYE, a Finnish university spin-off founded in 2014, is the closest Finnish example. It builds small synthetic-aperture radar satellites, which can image the Earth through cloud and darkness. Its chief executive, Rafal Modrzewski, says ICEYE has delivered complete satellite systems to Poland, Greece and Portugal within twelve months of signing, in an industry where one satellite used to take five years. He says the company builds about 50 satellites a year and aims to reach 100 a year by the end of 2027 (Defense News, 2026). He also says an ICEYE system costs a tenth of a legacy one. That is the company’s own claim, and public contracts cannot confirm it. Germany’s three-satellite SARah reconnaissance system was contracted in 2013 for €816 million (SpaceNews, 2013). Poland’s 2025 agreement with ICEYE, worth about €200 million, covered an initial three satellites, a mobile intelligence platform and an option for more (ICEYE, 2025). The two purchases differ in scope, in capability and by more than a decade, so they show only that a different kind of supply now exists, not how much cheaper it is. Demand changed as well. ICEYE has said the US halt of intelligence sharing in March 2025 sharpened European interest in sovereign access to satellite intelligence, and it has since signed contracts with the armed forces of Poland, Portugal, the Netherlands and Finland (Defense News, 2025; 2026). Even so, co-founder Pekka Laurila compares the company’s workshop to a studio where a few sports cars are assembled by hand (Yle, 2025). By its own account, the production model is still maturing.
The broadest version of the question concerns information. Epoch AI, a research institute that tracks artificial intelligence, measured how quickly the price of reaching a given level of AI performance fell over roughly the three years to early 2025. Depending on the task, the decline ranged from 9 to 900 times per year. The price of matching GPT-4’s performance on a set of PhD-level science questions fell about 40 times per year. The researchers caution that the fastest declines come from the shortest data series and may not last (Epoch AI, 2025). Many knowledge-work products, such as market overviews, research summaries and routine reports, use information as their raw material, and most of their cost is processing. As processing becomes much cheaper, buyers can see more clearly how much of the price paid for processing and how much paid for judgement about what matters. How large each share turns out to be remains an open question.
Across these cases, the materials were never the secret. Rocket builders knew what aluminium cost. The price of semaglutide’s active ingredient could be traced in trade data. Transformer makers knew their steel bills. What held prices up was the arrangement around the product: who was allowed to make it, how many units were ordered, how much failure the buyer would tolerate and whether the buyer could credibly go elsewhere. The disruptions came when one of those terms changed, through a commercial entrant, an expiring patent, overcapacity or a buyer suddenly in a hurry. For anyone looking for the next opening, the more useful question is not what something costs to make, but which part of that arrangement is about to change.
In your own industry, which of those terms is holding a price up, and how long will it hold?
Sources
- Schachter, H. (2023). “Does Elon Musk’s success suggest callous leadership beats compassionate leadership?” The Globe and Mail (review of Walter Isaacson, Elon Musk, Simon & Schuster, 2023). https://www.theglobeandmail.com/business/careers/management/article-does-elon-musks-success-suggest-callous-leadership-beats-compassionate/
- Jones, H. W. (2018). “The Recent Large Reduction in Space Launch Cost.” 48th International Conference on Environmental Systems, NASA Ames Research Center. https://ntrs.nasa.gov/citations/20200001093
- Barber, M. J., Gotham, D., Bygrave, H., Cepuch, C. (2024). “Estimated Sustainable Cost-Based Prices for Diabetes Medicines.” JAMA Network Open. https://jamanetwork.com/journals/jamanetworkopen/fullarticle/2816824
- Reuters (23 March 2026). “Indian drugmakers flood market with cheaper versions of Novo’s Ozempic, Wegovy.” https://www.reuters.com/business/healthcare-pharmaceuticals/indian-drugmakers-flood-market-with-cheaper-versions-novos-ozempic-wegovy-2026-03-23/
- The Hindu BusinessLine (21 March 2026). “Generic semaglutide versions roll out at prices pegged 80% less than Novo Nordisk’s Ozempic.” https://www.thehindubusinessline.com/companies/generic-semaglutide-versions-roll-out-at-prices-pegged-80-less-that-novo-nordisks-ozempic/article70766720.ece
- BBC (3 June 2026). “Why Canadians can now get cheaper generic Ozempic, and Americans can’t.” https://www.bbc.com/news/articles/c142y4p2eyxo
- BloombergNEF (9 December 2025). “Lithium-Ion Battery Pack Prices Fall to $108 Per Kilowatt-Hour, Despite Rising Metal Prices.” https://about.bnef.com/insights/clean-transport/lithium-ion-battery-pack-prices-fall-to-108-per-kilowatt-hour-despite-rising-metal-prices-bloombergnef/
- Energy-Storage.News (10 December 2025), on the 93% decline since 2010. https://www.energy-storage.news/li-ion-battery-pack-prices-fell-8-since-last-year-despite-metals-prices-rising-bloombergnef-says/
- Reuters (24 October 2023). “NATO urges common standards and curbs on protectionism to boost artillery output.” https://www.reuters.com/world/nato-urges-common-standards-curbs-protectionism-boost-artillery-output-2023-10-24/
- Defense One (27 November 2023). “In race to make artillery shells, US, EU see different results.” https://www.defenseone.com/business/2023/11/race-make-artillery-shells-us-eu-see-different-results/392288/
- Defense News (20 June 2024). “European ammo firms tell EU to ‘hurry up’ with 155mm shell aid top-up.” https://www.defensenews.com/global/europe/2024/06/20/european-ammo-firms-tell-eu-to-hurry-up-with-155mm-shell-aid-top-up/
- Wood Mackenzie (2 April 2024). “Supply shortages and an inflexible market give rise to high power transformer lead times.” https://www.woodmac.com/news/opinion/supply-shortages-and-an-inflexible-market-give-rise-to-high-power-transformer-lead-times/
- Wood Mackenzie (13 August 2025). “Transformer troubles: manufacturing and policy constraints hit US transformer supply.” https://www.woodmac.com/news/opinion/transformer-troubles-manufacturing-and-policy-constraints-hit-us-transformer-supply
- NATO (4 April 2023). “Finland joins NATO as 31st Ally.” https://www.nato.int/en/news-and-events/articles/news/2023/04/04/finland-joins-nato-as-31st-ally
- Hollenbeck, N. et al. (2025). “Calculating the Cost-Effectiveness of Russia’s Drone Strikes.” CSIS. https://www.csis.org/analysis/calculating-cost-effectiveness-russias-drone-strikes
- Jensen, B., Atalan, Y. (2025). “Drone Saturation: Russia’s Shahed Campaign.” CSIS. https://www.csis.org/analysis/drone-saturation-russias-shahed-campaign
- Rumbaugh, W. (2024). “Cost and Value in Air and Missile Defense Intercepts.” CSIS. https://www.csis.org/analysis/cost-and-value-air-and-missile-defense-intercepts
- Defense News (25 June 2026). “ICEYE to double radar-satellite capacity by late 2027 as demand surges.” https://www.defensenews.com/global/europe/2026/06/25/iceye-to-double-radar-satellite-capacity-by-late-2027-as-demand-surges/
- Defense News (17 November 2025). “ICEYE sees role as Europe’s defense space-intelligence linchpin.” https://www.defensenews.com/global/europe/2025/11/17/iceye-sees-role-as-europes-defense-space-intelligence-linchpin/
- ICEYE (14 May 2025). “ICEYE to provide SAR satellites for the Armed Forces of Poland.” https://www.iceye.com/newsroom/press-releases/iceye-to-provide-sar-satellites-for-the-armed-forces-of-poland
- SpaceNews (2 July 2013). “OHB Signs Contract for Germany’s Next-gen Radar Satellites.” https://spacenews.com/36091ohb-signs-contract-for-germanys-next-gen-radar-satellites/
- Yle News (15 November 2025). “Finland’s Iceye emerges as fast-rising star in private space race.” https://yle.fi/a/74-20194313
- Cottier, B., Snodin, B., Owen, D., Adamczewski, T. (2025). “LLM inference prices have fallen rapidly but unequally across tasks.” Epoch AI. https://epoch.ai/data-insights/llm-inference-price-trends