Finland Shares the Risk. Who Keeps the Upside?
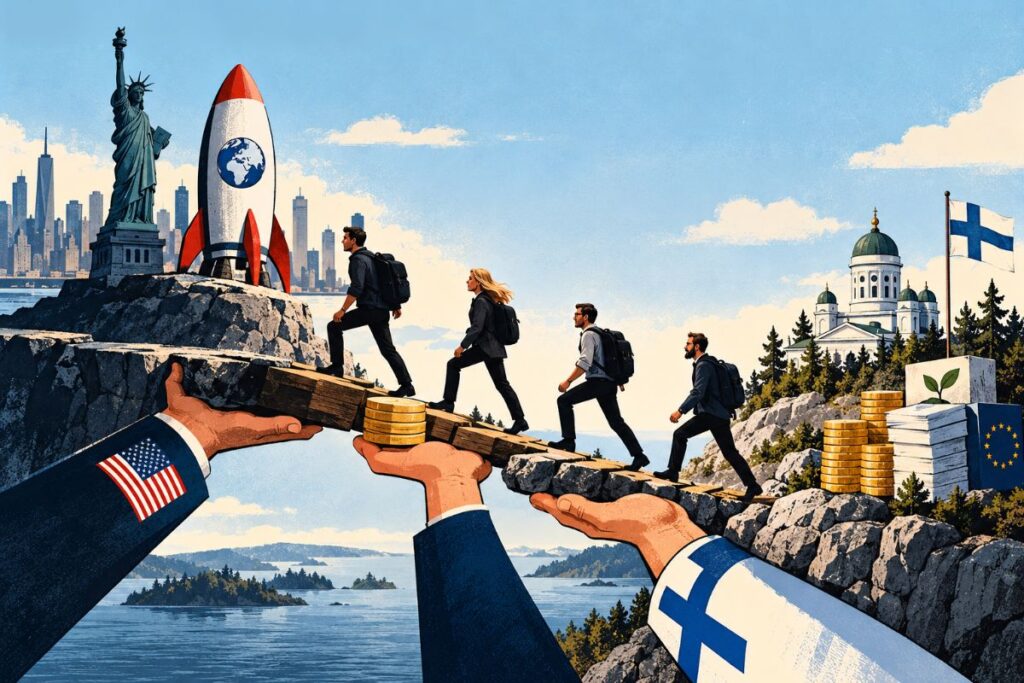
The debate over angel money versus taxpayer money in Finnish innovation assumes two separate pots. The data says otherwise. In the same companies, private angels and public funders carry the earliest and riskiest years side by side, and the larger question is who captures the value those years create once a company is ready to scale or sell.
When a Finnish startup moves its headquarters to the United States, it usually does not stop paying tax in Finland. In the common “US flip”, shareholders swap their shares for shares in a new US parent company, the Finnish company usually stays on as a subsidiary, and Finland keeps taxing its profits. The flip itself does not change who ultimately owns the company: the same shareholders keep their stakes, now held through the US parent. What changes is the parent’s legal home, and with it, often, where later funding rounds, an eventual sale and strategic decisions take place.
The clearest picture comes from a study published on 20 October by the Finnish Startup Community, a member association of growth companies and investors that also does policy advocacy, and FiBAN, the Finnish Business Angels Network. Its authors, economist Amir Hassan of the Startup Community and data scientist Ivan Helin of FiBAN, linked FiBAN’s records of 1,617 angel-backed companies to Statistics Finland registers and to grant and loan data from Business Finland, the state agency that funds research and innovation in Finnish companies (Angel-backed Firms in Finland 2026).
The firms matter to the economy. In 2024 the 1,239 of them still filing accounts had combined revenue of €5.97 billion, about 23,800 personnel and €281 million of R&D spending, roughly 4.6 percent of Finland’s private R&D (STT release). The study describes these as historical developments, not proof that angel money caused them.
The more telling number sits further down the report. Of the 1,617 firms, 1,214, or 75 percent, had also received public grants or loans from Business Finland, more than €1.4 billion in total since 2010. Part of that reflects emergency grants: the report notes public funding peaked in 2020 because of pandemic support. The study did not include other public funders, such as Finnvera, the state-owned financing company, or Tesi, the state investment company, so the figure does not capture all public money in these firms. Alongside that sits about €6.5 billion of follow-on venture capital, while FiBAN members have reported €526 million of angel investment in all since 2011. The figures cover different scopes and periods, and FiBAN’s own data relies on what members report, so they show the shape of the funding rather than precise ratios.
That shape is consistent. Angels typically write the first small cheque, a median of €20,000, around two years after founding. Public money runs alongside them, and the large rounds come later, mostly from abroad. Of the record €1.9 billion Finnish startups raised in 2025, about 72 percent came from foreign investors, according to the Finnish Venture Capital Association (FVCA, Venture capital in Finland 2025). In Finland the question was never angel money or taxpayer money. It is how the two work together, and what happens to their shared bet when the big money arrives.
The public side of that bet is shifting. Business Finland granted €577.6 million of innovation funding, grants and loans combined, to companies in 2025. Startups received €122.3 million, or 21 percent, against 40 percent in 2019, while large companies’ share rose from 35 to 54 percent (Business Finland, Tulokset ja vaikutukset 2025). On top of that came €312 million of investment grants for large clean transition projects and about €2.0 billion of tax credits for 37 large industrial investments (Business Finland, tilinpäätös 2025).
Statistics Finland notes that the tax credit alone exceeds all direct business subsidies granted that year combined (Tilastokeskus). The Ministry of Economic Affairs and Employment puts total direct business subsidies, including loans that are repaid, at €4.2 billion in 2025, or 1.48 percent of GDP (TEM). Some of the startup community already reads this as a problem. Slush, the Helsinki startup event and foundation, put “public funding toward early-stage startups rather than established companies to enhance creative destruction” among ten reform proposals it sent to Prime Minister Petteri Orpo (National Coalition Party) this spring (Slush).
When the large money arrives, it often brings a move. Mario Draghi’s 2024 report on EU competitiveness, as cited by the European Investment Bank, estimates that about 10 percent of EU scaleups relocate abroad, around 85 percent of them to the United States, and that nearly 30 percent of European unicorns moved their headquarters between 2008 and 2021. The EIB’s own interview study, published in January, found every one of its 71 relocated companies had moved only partially, keeping R&D in the EU, and named investors’ preference for a US company as the most significant immediate trigger (EIB; Science|Business). The Commission’s Joint Research Centre puts the headquarters relocation rate of VC-backed startups at 3.3 to 4.3 percent, about ten times that of comparable firms without venture capital (JRC).
Finland has recently made that path smoother. Since the start of 2026, Finnish shareholders can swap into a US or UK parent company without immediate capital gains tax, with the tax deferred until the new shares are sold. The deferral is clawed back if the shareholder moves outside the EEA within five years (Borenius). For the Finnish founders and investors who stay resident, the eventual gain is still taxed in Finland.
The leak is at the edges. Finland has no personal exit tax. A Finnish citizen who moves abroad normally remains tax resident for the year of the move and three more (Vero), after which a later sale can fall outside Finnish tax. The Ministry of Finance studied a personal exit tax in 2020, estimated it would raise between zero and €50 million a year and did not recommend it (VM). A later draft was dropped from the legislative plan in November 2022 (BOWA).
The public money has its own exit rule. Business Finland’s grants and loans work differently. Loans are repaid with interest in any case, though they can be partly or fully waived if a project fails (Business Finland, Changes in financing and ownership). For grants, a funded company must notify the agency if it moves its business abroad or sells project IP within five years of the final payment, and if control moves outside the European single market, Business Finland may, but is not required to, demand the grant back (Business Finland funding terms). Israel’s Innovation Authority uses a different design. Its startup grants are repaid as royalties of 3 to 5 percent of revenue once the product sells, and moving funded know-how out of Israel can cost up to six times the grant plus interest, or three times if R&D jobs stay for three years. The authority reports the median startup repayment in such transfers in 2005 to 2024 was under 1.5 times (Israel Innovation Authority).
Whether the state should be in this business at all is an old argument with live evidence on both sides. Joseph Schumpeter, in Capitalism, Socialism and Democracy (1942), described growth as creative destruction, new firms displacing old ones. Milton Friedman, in Capitalism and Freedom (1962) and in Free to Choose (1980), written with Rose Friedman, argued that markets allocate resources better than governments, in part because officials spend other people’s money on other people’s priorities. Mariana Mazzucato’s The Entrepreneurial State (2013) argues the opposite case, that public money took many of the early, high-risk bets behind technologies private investors later scaled.
Finnish data supports parts of both. An evaluation by Etla, the Research Institute of the Finnish Economy, of Tekes R&D funding for the European Commission found the grants raised firms’ R&D spending and R&D hiring, but found no effect on productivity and signs that subsidies keep less productive firms alive longer (Etla / Business Finland, 2020). That is Schumpeter’s concern measured in Finnish registers. A study led by VTT, the state-owned research company, covering 1995 to 2018 found that funded firms were 3.7 to 6.5 percentage points more likely to bring a significant innovation to market than a matched control group, including small and young firms (VTT).
Shifting the job to private investors through the tax system is not automatically better either. After the employee stock option reform this spring, covered in Relefy’s Finland’s startup community just got what it fought ten years for!, the Finnish Startup Community named its next step: decisions that attract more private capital to growth companies, such as a tax incentive for reinvesting returns, as in the United States and Sweden (Finnish Startup Community). Sweden’s own growth analysis agency, Tillväxtanalys, evaluated its investor deduction in 2023. It found the deduction steered money toward firms with weaker growth prospects, drew mostly inexperienced investors and did not raise risk capital overall (Tillväxtanalys). The agency’s own conclusion is that such an incentive only works if it draws in competent investors able to pick and support promising firms.
The global argument cuts both ways too. If one country subsidises and another does not, firms may follow the money, and the EU now allows member states to match the aid a company would receive outside the Union (TEM, Yritystukien kehitys 2012–2025). Yet the founders the EIB interviewed named access to markets and growth capital, simpler regulation and experienced sales talent as the main reasons they left. That is the logic behind EU Inc, the optional single European company form the Commission proposed in March, which Parliament and member states aim to agree on by the end of 2026. Parliament’s lead negotiators have yet to agree among themselves; on 14 October they failed for a second time to settle how employee board representation would apply (European Commission; European Parliament; Rapporteur; Agence Europe). Allied For Startups, the Brussels startup association, welcomed it with a warning: “On paper, it surely looks European, but in practice it may feel national” (Allied For Startups).
So the choice in front of Finland is less about angels versus taxpayers than about what each euro is meant to do. Public money already sits in three of four angel-backed firms. Business Finland’s loans come back with interest, but a grant asks nothing back from a company that succeeds. The main exit condition is that Business Finland may reclaim a grant if control moves outside the European single market within five years of the last payment. Should early public money step back and leave the bet to private investors, stay a grant, or start behaving more like a stake in what it helps build?
Sources
- Finnish Startup Community and FiBAN, Angel-backed Firms in Finland 2026 (report, October 2026) and press release, 20 October 2026
- Business Finland, Tulokset ja vaikutukset 2025 and Tilinpäätös 2025
- Business Finland, Funding for companies’ R&D activities, terms and conditions, 1 January 2026, and Changes in financing and ownership
- Statistics Finland, Yritystukea myönnettiin 1 415 miljoonaa, 28 April 2026
- Ministry of Economic Affairs and Employment, Yritystukien määrä laski, 18 June 2026, and Yritystukien kehitys 2012–2025
- Slush, Finnish Founder Survey results and ten reform proposals, April 2026
- European Investment Bank, Drivers of relocation by innovative EU startups and scaleups, January 2026; Science|Business, coverage of the study, 15 January 2026
- European Commission Joint Research Centre, Is Europe losing its startups?
- Borenius, Share Swap Reform: Opening the Door to International Funding, 19 March 2026
- Finnish Tax Administration, Finnish citizens and the 3-year rule
- Ministry of Finance, Maastapoistumisvero: mistä on kyse ja mistä ei?, 14 February 2020; BOWA Legal, Maastapoistumisveron piti tulla käyttöön vuonna 2023
- Israel Innovation Authority, Royalties and Intellectual Property
- Etla for Business Finland, Evaluation of Tekes R&D Funding for the European Commission, 2020
- VTT, Supporting innovation produces measurable impact (InnoPact study, 31 August 2021)
- Finnish Startup Community, Key flaw in employee stock option reform addressed, 2 September 2026
- Tillväxtanalys, Evaluation of the Swedish investor deduction, Working Paper 2023:01 (Swedish summary)
- Finnish Venture Capital Association, Venture capital in Finland 2025, April 2026
- Rapporteur, EU Inc again stumbles over workers’ rights in Parliament, 14 October 2026; Agence Europe, Lack of agreement among European Parliament rapporteurs leads to postponement of committee vote on 28th regime, 6 October 2026
- European Commission, Commission presents proposal for EU Inc., 18 March 2026; European Parliament, EU Inc.: what is the 28th regime?
- Allied For Startups, First reaction to the EU Inc. proposal, 18 March 2026
- Joseph Schumpeter, Capitalism, Socialism and Democracy (1942); Milton Friedman, Capitalism and Freedom (1962); Milton and Rose Friedman, Free to Choose (1980); Mariana Mazzucato, The Entrepreneurial State (2013)