In Liu Cixin’s The Three-Body Problem, an alien civilization discovers Earth and decides to invade. Their fleet leaves immediately. The journey will take 400 years.
Forty years in, their scientists run the numbers again and panic. Human civilization, stable and uninterrupted, is advancing far faster than their own, a society repeatedly knocked back to zero by an unstable star system. Run the gap forward four centuries and it doesn’t close. It reverses. So they build a weapon, not to destroy human civilization, but to freeze its rate of learning: a device that sabotages the experiments humanity would need to keep advancing. A civilization with a multi-century head start, terrified not of where humans currently stood, but of how fast they were closing the distance.
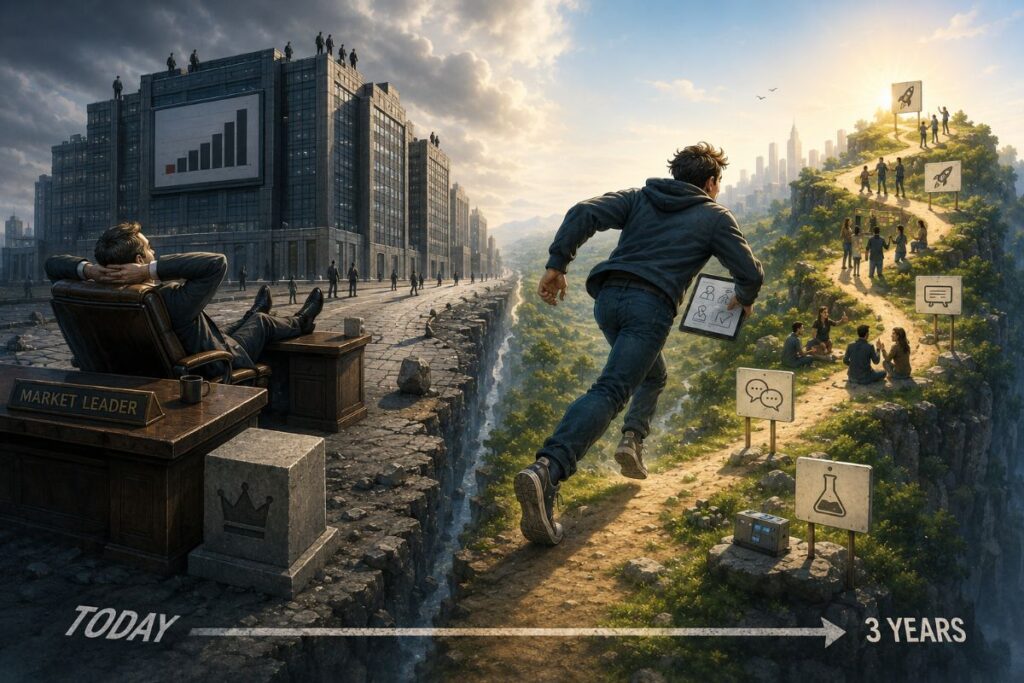
They didn’t fear the snapshot. They feared the slope.
That distinction has a real name in research on motivation and decision-making: displacement, how far you’ve come, versus velocity, how fast you’re currently moving. Almost everyone defaults to judging displacement, because it’s visible at a glance. Velocity has to be inferred, and most people don’t bother.
This isn’t a claim that current capability is irrelevant. A team with no product and a steep learning curve still has no product. The claim is narrower: if you’re trying to predict what something looks like in three to five years, rate of change predicts it better than current position does, and the people holding the position rarely act like they know that.
Blockbuster had over 9,000 stores and tens of millions of customers in 2000. When Netflix’s founders flew to Dallas that year and offered to sell the company for 50 million dollars, Blockbuster’s CEO turned them down without much consideration, and Netflix’s own co-founders later said the room struggled not to laugh. Ten years later Blockbuster was bankrupt. Google invented the architecture underneath modern AI and then watched a much smaller lab put a simple interface on an existing model, ship it, and learn faster from real usage than Google’s internal review process could move. Zara rebuilt its supply chain so a trending item goes from sketch to shelf in two to three weeks instead of a season, and became the world’s largest fashion retailer by making its rate of adjustment the actual product, while competitors kept competing on scale. Three industries, the same shape: the giant has more to protect, so changing course costs it more, while the challenger has nothing to protect and therefore nothing holding its velocity down.
Here’s the part that should be encouraging rather than just observational: the people whose entire job is pricing risk for a living have already built this into the math.
Venture capital’s standard valuation framework doesn’t price a company on what it currently has. It prices a company on how far it has moved through the stages where things typically go wrong. A startup at the idea stage, by industry data from Dealroom and PitchBook, succeeds about 6% of the time. By the growth stage, that probability is closer to 33%. Because a fund needs its winners to cover its losers, that gap in survival odds gets converted directly into required return: an idea-stage company needs to be priced as if it could return roughly 200 times the investment to make the math work, while a growth-stage company needs a fraction of that multiple, because it has already proven the things that used to be unknown. Nothing about the company’s absolute size changed. What changed is that it demonstrated a rate of de-risking, and the entire venture industry has formalized that rate into the number that determines what a company is worth today. The market for funding new companies is, structurally, a market that prices velocity rather than position.
Public markets take longer to catch up, but they get there. Jay Ritter’s 1991 study tracked 1,526 companies that went public in the U.S. between 1975 and 1984, comparing them to matched firms over the following three years. The newly public companies underperformed their matches by about 17 percentage points cumulatively over that period. The worst performers were the youngest companies and the ones that had gone public riding the highest initial enthusiasm, exactly the firms whose pitch was “look how fast we’re moving” with the least track record to back it up. The best performers were older, more established firms with a longer real history of execution behind them. Read carefully, this isn’t a contradiction of the velocity argument. It’s the necessary other half of it. The market initially pays for the appearance of momentum, a hot story, a generation-defining narrative, and then spends three years correcting that mistake. The correction falls hardest on companies whose velocity was theater rather than substance. What actually held value afterward wasn’t size and it wasn’t hype. It was demonstrated, sustained capability to keep moving, the same thing the VC Method is pricing on the way in.
A multi-century alien fleet, a Dallas boardroom in 2000, a venture capitalist’s spreadsheet, and three years of public market data are all running the same calculation from different angles, and none of them are calculating your current size. They’re trying to estimate your slope, sometimes too late, sometimes formally and on purpose, but always your slope.
If you’re a startup wondering whether you stand a chance against someone many times your size, the lack of size might be exactly what makes you faster. History keeps siding with the smaller, quicker mover. The giant isn’t waiting to see if you’ll catch up. It’s hoping you won’t notice you already are.
Sources
Liu Cixin, The Three-Body Problem (Tor Books, English translation, 2014)
Zou, X., Scholer, A. A., & Higgins, E. T. (2014). In Pursuit of Progress: Promotion Motivation and Risk Preference in the Domain of Gains. Journal of Personality and Social Psychology, 106(2), 183–201. https://doi.org/10.1037/a0035391
Hastings, R., & Meyer, E., No Rules Rules: Netflix and the Culture of Reinvention (excerpted in Marketplace, 2020): https://www.marketplace.org/story/2020/09/08/ceo-reed-hastings-on-how-netflix-beat-blockbuster
Randolph, M., That Will Never Work: The Birth of Netflix (2019), on the 2000 Blockbuster meeting
Vaswani, A. et al. (2017). Attention Is All You Need. https://arxiv.org/abs/1706.03762
Ferdows, K., Lewis, M. A., & Machuca, J. A. D. (2004). Rapid-Fire Fulfillment, on Zara’s design-to-shelf supply chain: https://www.iberglobal.com/files/2018/zara_case_supply_chain.pdf
Equidam, “The Logic of the VC Method for Startup Valuation”: https://www.equidam.com/vc-method-startup-valuation/
Ritter, J. R. (1991). The Long-Run Performance of Initial Public Offerings. Journal of Finance, 46(1), 3–27. https://site.warrington.ufl.edu/ritter/files/The-Long-Run-Performance-of-Initial-Public-Offerings-1991-03.pdf